Digital Enforcement and Procedural Reform: Unpacking Kenya’s Finance Bill 2026

Sponsored by Deloitte East Africa
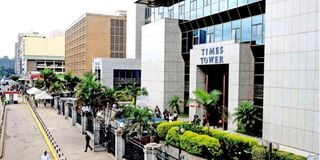
Times Tower, the Kenya Revenue Authority's head office in Nairobi.
By Ann Magondu & Anthony Munyare
Kenya’s Finance Bill 2026 marks a new phase in the country’s tax administration framework. It seeks to introduce sweeping changes across multiple tax laws, including major reforms to the Tax Procedures Act (TPA). The proposals reflect a major push by the Kenya Revenue Authority (KRA) to widen the tax base and modernize compliance through a data driven tax administration even if it means rethinking some measures introduced only a year ago.
The Government aims to build a more robust, data-driven tax regime to raise revenue while preserving equity tenets of taxation. This direction is already reflected in KRA’s recent performance, with the Authority attributing new tax receipts to digital interventions that have improved how taxes are assessed, collected and monitored. Notably, KRA has said it collected KES 7.8 billion this year from about 97,000 individuals and entities that had previously not paid direct taxes, underscoring how digital transformation is helping shift tax administration from a largely manual, retrospective model to a more real-time, data-centric system.
The KRA will be empowered to leverage its digital platforms including the iTax online system and the new Electronic Tax Invoice Management System (eTIMS) to automatically generate pre-filled tax returns for taxpayers while still allowing taxpayers to self-file. This step, previewed by a pilot program of pre-populated returns, signals a shift toward a “dual assessment” model in which both taxpayers and the tax authority prepare returns in parallel. Further, the KRA will be authorized to issue tax assessments based on data already in its possession including withholding tax deducted at source and electronic invoices submitted via eTIMS.
In a similar vein, the proposals extend reporting obligations to virtual asset service providers (VASPs) to provide information in respect of all the virtual assets users with which they maintain a relationship. Failure to comply exposes the VASPs to stiff penalties. Kenya would also be empowered to join international information-sharing agreements for crypto assets, aligning its oversight with global standards like the OECD’s Crypto-Asset Reporting Framework, a global initiative aimed at promoting the automatic exchange of information between countries to combat tax evasion risks associated with cryptocurrencies and digital assets.
On the flip side, the drive for stricter compliance includes proposals that expand KRA’s enforcement powers, raising concerns about taxpayer safeguards. A notable measure would allow the tax authority to issue “agency notices” that would result in freezing a taxpayer’s bank funds even when a tax dispute is under appeal. This “pay-first, argue-later” approach negates the principle of fair trial, which includes the right to be presumed innocent until the contrary is proved. The right to appeal an adverse decision is a fundamental component of the rule of law and the constitutional rights to fair administrative action and access to justice anchored in the supreme law of the land, the Constitution of Kenya, 2010.
Another proposal would repeal a provision that excused a payer from liability for unwithheld tax if the recipient had already paid the related principal tax, thus reviving the risk of double taxation on the same income. Likewise, ending a year-old avenue that allowed businesses to offset overpaid domestic taxes against import VAT is expected to squeeze the cash flows of import-heavy sectors like petroleum importers.
The proposed consolidation of the anti-tax-avoidance rules under the TPA coupled with a leverage on the digital data (such as e-invoices) will help in curbing and detection of avoidance. Whilst this may improve consistency in enforcement, it comes with a hefty 200% penalty on tax deemed avoided – making taxpayer recourse essential. Additionally, there is a proposal to count weekends and public holidays within the timeline for lodging tax appeals or objections, effectively shortening the time available for recourse.
Pragmatic reforms
For balance, the Bill includes pragmatic reforms to ease compliance burdens and foster a more business-friendly climate. It would scrap the year-old requirement for importers to present a Certificate of Origin for all goods, a rule widely seen as a non-tariff barrier. It further streamlines registration by letting deregistered taxpayers reinstate their former Personal Identification Number (PIN) if they re-enter the tax system. Also, foreign investors will get relief by not being required to obtain a PIN to open an investment bank account, a small but symbolic step to reduce red tape and attract capital inflows.
The Bill also revives a tax amnesty program that lapsed in 2025, giving taxpayers until December 2026 to clear outstanding principal tax for period prior to 31 December 2025 with all resultant interest and penalties being waived. The previous tax amnesty that covered the tax periods ended by 31 December 2023 yielded additional tax revenue of KES. 43.9 billion while offering businesses a chance to settle old liabilities without punitive costs.
Another provision addresses the challenges of new e-tax systems by requiring KRA to let taxpayers explain why they failed to use electronic invoicing or filing systems before any fines are imposed, acknowledging that technical glitches can hinder compliance. At the same time, the Bill sets new minimum penalties for not using mandated electronic tax systems (with minimum fines of KES. 100,000 for companies), underlining KRA’s seriousness about digital compliance. Lastly, in a nod to efficiency, the Commissioner would be allowed to waive penalties and interest caused by its own system errors on smaller amounts without Treasury approval.
These tax procedure changes illustrate the delicate balance between aggressive revenue mobilization and maintaining a fair, predictable tax environment. The KRA is under pressure to maximize tax collections via technology-driven oversight and stricter rules, but too heavy a hand could erode business confidence and undermine Kenya’s ease of doing business As the global economy becomes increasingly digital, KRA will need to continue monitoring transactions in this space to keep pace with emerging business models to grow tax revenues and seal leakages.
Anthony Munyare ([email protected]) and Anne Magondu ([email protected]) are Tax Manager and Senior Manager at Deloitte East Africa respectively. The views presented are their own and not necessarily those of Deloitte.