Tax exemptions for charitable trusts, under Kenyan law, are meant to create a win-win situation where the institution gets relief as the State is certain that most funds collected are used for public good.
The catch, however, is that the Kenya Revenue Authority (KRA) must do a deep dive into books of accounts to ensure that funds are being spent on the benevolent activities claimed by the charitable organisation.
One such deep dive has put Knowledge Empowering Youth (KEY) Trust, a charitable organisation founded by a daughter of former Cabinet minister Nicholas Biwott, on a collision course with KRA.
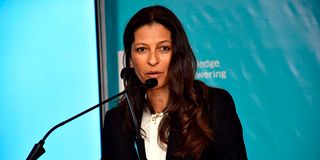
Rita Field-Marsham, who once made headlines for declining a 1/14th share of her father’s multibillion-shilling estate, is the founder of KEY Trust.
Kenya Scholar Access Programme (KenSAP) Board of Directors Chairman Charles Field-Marsham addresses participants during a charity gala dinner in Nairobi on May 21, 2025.
Photo credit: Bonface Bogita | Nation Media Group
Ms Field-Marsham, her husband Charles Field-Marsham and Wandia Gichuru – the founder and CEO of Vivo Activewear and ShopZetu – sit on KEY Trust’s Board of Trustees.
KEY Trust, which operates in Kenya and Canada, was seeking renewal of its income tax exemption in July, 2025 through an application to the KRA.
While combing through KEY Trust’s books of accounts, KRA officers flagged more than Sh25 million spent overseas which, to the taxman, raised questions on whether the organisation was using its funds strictly for local charitable activities.
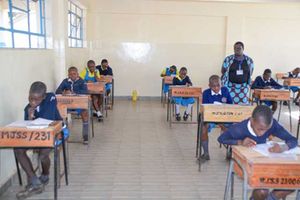
The first initiative, KEY Libraries, works with public primary and secondary schools to establish and improve libraries by providing schools with books, furniture, computers, smart boards and other learning materials aimed at improving the learning environment.
The trust’s second arm, the Kenya Scholar Access Program (KenSAP), where Ms Field-Marsham serves as a Board director, supports academically gifted students from disadvantaged backgrounds to access university education.
After reviewing the application, the Commissioner for Micro and Small Taxpayers rejected the exemption in March, 2026.
The taxman’s main concern was that the Trust had made what the tax authority considered large payments to KenSAP Limited, described as a separate entity.
The Commissioner took the position that the payments raised questions about whether the Trust's income was being used exclusively for charitable purposes.
In its response to the appeal, KRA made several allegations against the charitable organisation, which had not been raised in the taxman’s decision rejecting KEY Trust’s application for renewal of exemptions.
KRA claimed that KEY Trust had violated the Income Tax (Charitable Organisations and Donations Exemption) Rules, 2024 by spending more than Sh25 million overseas, having non-resident beneficiaries, failing to cater for persons with disability and failing to furnish itemised payment summaries and supporting documents.
KRA also questioned how much KEY Trust was paying its staff and trustees, and alleged that the organisation was accumulating big sums of money instead of spending it on charitable activities.
Vivo Fashion Group Co-Founder and CEO Wandia Gichuru at her offices on May 20, 2026.
Photo credit: Francis Nderitu | Nation Media Group
KEY Trust then filed an application seeking to have KRA’s response struck out of the record, arguing that the taxman had introduced allegations which were not in the rejection decision hence not part of the dispute and proceedings before the tribunal.
The Trust argued that it was unfair to introduce these issues at the appeal stage, and that the Commissioner ought to have informed KEY Trust of those issues when considering the tax exemption application so as to give the organisation an opportunity to respond before the rejection.
KRA insisted that it had not invented new reasons for rejecting the exemption and was only explaining in detail why KEY Trust had not met the legal requirements for income tax exemptions.
The Commissioner maintained the information came from the trust’s own financial statements, pleadings and other documents filed before the tribunal.
The tribunal ruled that KRA had introduced new grounds at the appeal stage, against legal practice rules and fairness to KEY Trust.
The Tribunal held that KRA was only allowed to introduce additional evidence to explain grounds contained in the rejection decision it issued to KEY Trust in March, 2026.
“The Tribunal has considered whether a lesser order would suffice, such as permitting those paragraphs to stand as evidentiary material only. The Tribunal rejects that course as it would leave the Appellant/Applicant (KEY Trust) to answer the same allegations in substance while denying it any remedy, and would obscure the very line between defending a decision and remaking it,” the tribunal ruling states.
The Tribunal observed that the issues involving overseas expenditure, non-resident beneficiaries, persons with disabilities and abandoned children, payment records, remuneration and surplus accumulation could each independently have been used to reject the trust's exemption application hence were fresh grounds and not supporting details.
The Commissioner had also argued that all the issues ultimately fell under the broad requirement in the Income Tax Act that a charitable organisation must apply its income for the prescribed charitable purposes.
But the Tribunal rejected the idea that simply citing the broad statutory provision allowed the tax authority to introduce any number of new compliance failures later.
Instead of striking out KRA’s entire response, the tribunal only ordered for deleting the paragraphs which introduced the fresh grounds. The tribunal added that KRA is free to raise those grounds in a fresh rejection decision.
“Finally, the Tribunal has not overlooked the Respondent’s concern for the public revenue. Nothing in this Ruling prevents the Commissioner from acting upon the matters raised in paragraphs 14 to 39 by way of a fresh and properly reasoned decision, in which event the