East Africa is entering a new phase of geopolitical and commercial competition as Kenya, Tanzania and Uganda seek greater control over petroleum refining, storage, transportation and distribution, potentially reshaping the region’s energy map.
At the centre of the contest are Tanzania’s Port of Tanga and Kenya’s Lamu Port, while Uganda’s oil reserves and planned Hoima refinery could determine how crude and petroleum products move across the region.
In April, President William Ruto announced plans for a regional refinery at Tanga, saying Kenya, Uganda and Tanzania could use the facility to process crude from several East African producers. Nigerian industrialist Aliko Dangote said he was prepared to lead its construction.
“We are discussing that we are going to have a joint refinery in Tanga, to benefit all of us because that refinery is going to take on board the oil from DRC (Democratic Republic of Congo), the oil from Kenya, the oil from South Sudan, the oil from Uganda, and we will just need to build a short pipeline from Tanga to Mombasa and the finished product, we will use the pipeline that we jointly own with Uganda, so all our assets become profitable,” said President Ruto.
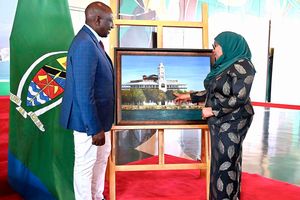
The announcement caught Tanzania off guard. President Samia Suluhu Hassan later questioned why the project had been announced without consultation with her government.
Uganda workers doing pipe work for the East African Crude Oil Pipeline at Hoima.
Photo credit: File | Nation Media Group
“When we were speaking inside there, I confronted Ruto and asked him, you went and announced a refinery in Tanga, why didn't I know about it? Now he will speak for himself on why he made that announcement,” Ms Samia said during a joint engagement in Dar es Salaam.
The disagreement was followed by a shift in Dangote’s refinery plans toward Kenya, with Lamu emerging as the proposed site.
The proposed Lamu refinery, estimated to cost Sh2 trillion and designed to process up to 700,000 barrels of crude a day, is scheduled for groundbreaking today.
Engineers India has secured a contract valued at more than Sh58.3 billion to provide project management and engineering services.
In August, Uganda National Oil Company, Tanzania Petroleum Development Corporation and Vitol Bahrain signed a memorandum of understanding to develop the Tanga Regional Energy Hub.
The project is expected to incorporate refining, storage, logistics, trading, distribution and related petroleum infrastructure which will transport Ugandan crude from the Lake Albert region to Tanga.
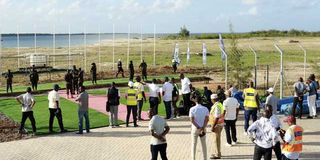
Construction works at the Tanga Port Marine Storage Terminal.
Photo credit: File
The agreement remains a framework rather than a fully financed project, meaning its final refinery configuration, investment requirements and implementation timetable are still being developed.
Tanzania’s Energy Minister Deo Nadeem described the hub as the next stage after the East African Crude Oil Pipeline (EACOP) which runs 1,443km from Kabaale, Hoima district in Uganda.
“The story we celebrate today did not begin in 2026. It began several years ago when Tanzania and Uganda made the courageous decision to deepen cooperation in the petroleum sector. As EACOP approaches completion, Tanzania and Uganda are not asking what comes next. Instead, we are answering that question together,” he said.
Uganda is simultaneously developing a 60,000-barrel-per-day refinery at Kabaale, intended primarily to meet domestic demand while supporting regional exports and petrochemical industries.
Uganda National Oil Corporation chief corporate officer Tony Otoa has described Hoima and Tanga as complementary rather than competing projects.
“The two refineries (Hoima and Tanga) will make sure we have energy security in the region. They won’t compete. I can’t speak for Lamu,” said Mr Otoa.
Uganda’s position reflects its strategy of maintaining several options as it moves toward commercial oil production. The country has committed its crude to the EACOP route into Tanzania while retaining links to Kenya’s petroleum infrastructure.
The pipeline was 92.7 per cent complete by the end of August, according to the pipeline company, bringing Uganda closer to first oil production. The project is designed to transport crude from Uganda’s Albertine Graben to the Chongoleani terminal near Tanga.
For Uganda, the Tanga project offers a downstream extension of infrastructure already being built for crude exports.
Importing finished petroleum products
The proposed hub could allow Kampala to move beyond exporting crude and importing finished petroleum products toward refining, storage and distribution within the region.
At the same time, Uganda has strengthened its position inside Kenya’s petroleum network.
UNOC acquired a 20.15 per cent stake in Kenya Pipeline Company through its initial public offering. Uganda says about 95 per cent of its petroleum imports currently enter through Kenya via the Port of Mombasa and KPC system.
This creates an unusual situation in which Uganda is diversifying its supply routes while taking a direct financial stake in one of Kenya’s most important regional energy assets.
The scale of the existing Mombasa market explains why the shift matters. KPC estimates regional petroleum demand at 13 million cubic metres in the 2024/25 financial year, including 7.5 million cubic metres for transit markets. It says 65 per cent of transit-market imports serving Uganda, South Sudan, Rwanda, eastern Democratic Republic of Congo and Burundi were received through Mombasa.
KPC expects transit imports through Mombasa to rise from 4.1 million cubic metres in 2024/25 to five million cubic metres by 2029/30.
It also concerns pipelines, storage terminals, shipping routes, trading systems and access to landlocked markets.
The issue was highlighted by President Yoweri Museveni on September 17 when he discussed Uganda’s decision to take greater control over petroleum procurement.
“The Republic of Uganda was buying petroleum products through middlemen in Kenya. Can you imagine that? And the person who woke me up first was a senator from Kenya,” Mr Museveni said at the groundbreaking of a 320-million-litre petroleum storage terminal in Kampala.
President Ruto has defended Kenya’s fuel-supply arrangements, challenging critics to compare the landed cost of petroleum products in Kenya and Uganda.
“Check the landed cost of petrol products between Kenya and Uganda and see which one is cheaper. We have a better model than even what Uganda is using today,” he stated.
Mombasa has an established petroleum logistics network, while Tanga is gaining strategic importance through EACOP. Lamu, meanwhile, is being positioned around a new deep-water port and a greenfield refinery that could eventually serve markets across East and Central Africa. The roots of the competition stretch back more than a decade.
Uganda and Kenya agreed in 2014 to develop a crude oil pipeline from Uganda’s Lake Albert oilfields to Kenya’s Lamu coast. The plan was abandoned in 2016 after Uganda opted for the southern route through Tanzania.
That decision produced EACOP, giving Tanga a strategic advantage in Uganda’s petroleum export infrastructure. The pipeline is now nearing completion, turning what was once a disputed corridor into the foundation for Tanzania and Uganda’s latest energy partnership.
The Lamu refinery represents a second attempt by Kenya to establish a major petroleum corridor linked to East Africa’s oil-producing economies.
Its strategic case rests partly on the Lamu Port-South Sudan-Ethiopia Transport corridor, which is intended to connect the Kenyan coast with northern Kenya, South Sudan and Ethiopia. The challenge, however, is feedstock.
Uganda’s crude is committed to EACOP and Tanga, while Kenya’s own crude production remains too limited to support a refinery of the proposed scale. South Sudan also lacks a functioning alternative pipeline route to Lamu.
The Lamu refinery may therefore initially depend substantially on seaborne crude imports unless new regional supply arrangements are developed.
Tanga has a different starting point; its crude supply is directly connected to Uganda through EACOP. But Tanga must still turn the proposed energy hub into a commercially viable refining and distribution centre, requiring substantial financing, additional infrastructure and sufficient regional demand.
Tanga has direct connectivity to Uganda’s crude and an established pipeline under construction. Lamu has a deep-water port, access to the LAPSSET corridor and the backing of Dangote, whose proposed refinery would be among Africa’s largest. Uganda’s Hoima refinery adds another layer to the equation.
Rather than choosing a single regional processing centre, Kampala is pursuing domestic refining while supporting the Tanga hub and maintaining its investment in KPC.
This could produce a more interconnected regional petroleum system, with crude moving through Tanzania, refined products travelling through multiple corridors and Mombasa retaining a major role in distribution.
It could also intensify competition between the Northern Corridor and Tanzania’s Central Corridor for markets in Uganda, Rwanda, Burundi, eastern DRC and South Sudan.
The East African Community will therefore face a test of whether competing national interests can be converted into complementary regional infrastructure.
The economic logic for more refining capacity is straightforward. East Africa has significant petroleum resources but remains heavily dependent on imported refined products, leaving economies exposed to international prices, shipping disruptions and geopolitical shocks.
The emerging projects seek to capture more value locally through refining, storage, petrochemicals and distribution.
Kenya's Lamu offers the possibility of transforming a relatively new port into a major energy and industrial centre, while Tanzania's Tanga provides an opportunity to turn the end point of EACOP into a broader petroleum and logistics hub.
For Uganda, the strategy offers several routes to monetise its oil while reducing dependence on imported fuel. The competition is therefore unlikely to be determined by refinery capacity alone.
The decisive factors will include crude availability, financing, construction timelines, pipeline connectivity, port efficiency, product pricing and the ability to secure long-term markets in landlocked economies.
What began as a regional proposal for a single refinery at Tanga has evolved into parallel energy strategies.
Kenya is betting on Lamu and the commercial strength of Dangote. Tanzania and Uganda are building around Tanga and EACOP, while Uganda is pursuing Hoima as its domestic refining anchor.
Mombasa remains the region’s established petroleum gateway even as Lamu and Tanga seek a greater share of the market.
The result is a changing East African energy map in which ports, pipelines and refineries are no longer separate projects but competing pieces of one regional value chain.
The projects will ultimately be tested by their ability to secure crude, attract financing, build infrastructure and deliver competitively priced petroleum products to regional markets.
East Africa’s energy future is consequently being shaped not by a single corridor, but by the parallel development of Tanga, Lamu, Hoima and the established Mombasa network.