For many parents, sending a child to university brings a second major expense after tuition: finding safe, affordable accommodation.
In Nairobi and other university towns, students compete for rooms that are close to campus, reasonably priced and equipped with basics like reliable water, electricity and internet.
As university enrolment rises, the demand for accommodation is creating a new opportunity in the property market. Developers and institutional investors are increasingly turning their attention to purpose-built student accommodation (PBSA) – buildings designed to house learners.
Developers and institutional investors are increasingly turning their attention to purpose-built student accommodation (PBSA).
Photo credit: Shutterstock
Clive Ndege, Head of Sales at Superior Homes Kenya Plc, says the growth of Kenya’s higher education is creating demand for specialised student housing.
The latest Kenya National Bureau of Statistics Economic Survey shows that university enrolment rose by nine per cent to 631,300 students in the 2024/25 academic year, from the previous year.
Public universities accounted for 522,900 students. The increase is putting pressure on accommodation, particularly around institutions where campus housing cannot accommodate every student.
For developers, this represents a large and recurring market. For students, the issue is more personal. A student living several kilometres from campus may spend hundreds of shillings on transport daily. A room that appears cheap can, therefore, become expensive once commuting costs are added.
This is one reason accommodation within walking distance or a short commute from campus has become increasingly attractive.
“Location is a critical consideration in accommodation because students want convenience and easy access to their institutions,” Ndege says.
The demand is also changing the nature of student housing. For years, much of the market consisted of converted houses, bedsitters and informal hostels. Some offer affordable accommodation, but facilities and management standards greatly vary.
PBSA seeks to formalise the market by combining accommodation with professional management and amenities designed around student life.
A typical development may have furnished rooms, controlled access, high-speed internet, study areas, laundry facilities, communal spaces and recreational amenities.
This has attracted institutional capital into a market that was previously dominated by individual landlords.
One of the most prominent examples is Acorn Holdings, which has developed student accommodation through the Acorn Student Accommodation Development REIT (ASA D-REIT) and Acorn Student Accommodation Income REIT (ASA I-REIT).
Acorn’s ASA I-REIT latest data reported an average occupancy rate of 87 per cent in 2024, illustrating the demand for student housing and the fact that occupancy is not automatically guaranteed. Its portfolio had partnerships with 96 institutions.
Acorn has previously estimated that Nairobi has more than 240,000 university and college students, with only a small proportion accommodated within campuses. This leaves private accommodation to fill a substantial part of the gap.
For property investors, one of the attractions of PBSA is the potential to generate more income from a development by renting rooms or beds individually. A conventional apartment might have several bedrooms but be leased to one household.
A purpose-built student residence can accommodate more people on the same site, with every room or bed generating rent. However, higher density comes with higher development and management requirements.
“Student accommodation is a specialised asset class. It requires careful consideration of the location, target market, affordability and how the property will be managed,” Ndege says.
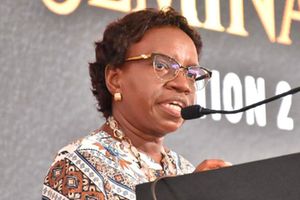
Clive Ndege, head of sales at Superior Homes, a real estate company. The property in Athi River has developed homes for retirees, complete with amenities that support the elderly.
Photo credit: Pool
This is important because the economics of PBSA differs from that of ordinary residential property. The developer must balance the number of beds against the cost of land, construction, financing, utilities and ongoing operations.
Land is particularly important. Student housing generally needs to be located close to universities or along convenient transport routes. But these are often areas where land prices have already risen because of strong residential and commercial demand.
A developer may, therefore, need to build upwards and maximise the number of beds on a site. That brings additional costs.
PBSA projects require lifts, fire-safety installations, water storage, back-up power, internet infrastructure and communal facilities. The buildings also need to meet county planning, environmental, health, accessibility and fire-safety requirements.
Financing can be another challenge. Large PBSA developments require substantial upfront capital, while rental income is generated only after the building has been completed and occupied.
This has made structures such as REITs increasingly relevant to the sector because they allow investors to pool capital into property projects.
Acorn’s experience demonstrates the scale of institutional financing involved. In 2023, Acorn and Bank Absa announced a Sh6.7 billion financing facility for 10 PBSA developments in Nairobi, expected to add about 12,000 beds.
The investment rush is, therefore, not simply about putting up more hostels. It is about creating professionally-operated real estate assets.
Student expectations are also changing. A learner looking for accommodation may consider internet connectivity almost as important as the size of the room.
University work increasingly involves online research, digital learning platforms, virtual meetings and electronic submission of assignments.
For parents, security is important. Controlled entry, CCTV, security personnel and well-managed common areas can influence the choice of accommodation.
Other amenities are increasingly becoming part of the competition between hostels. These include study rooms, laundry services, gyms, games areas, communal lounges and convenience shops.
“The market is moving towards accommodation where students can access several services in one place,” Ndege says.
This creates a different operating model from traditional residential rentals. A landlord renting out an apartment may deal with tenants mainly when rent is due or when repairs are required.
A PBSA operator has to manage room allocation, cleaning, maintenance, security, internet, utilities and relationships with students throughout the year.
As university enrolment rises, the demand for accommodation is creating a new opportunity in the property market.
Photo credit: Pool
In that sense, the business can resemble hospitality. The operator must also deal with the higher wear and tear associated with student accommodation.
Poor management can quickly result in complaints, vacancies and reputational damage.
The quality of the operator, management systems and services can determine whether students remain in a residence and recommend it to others.
Nairobi remains an important PBSA market because of its large concentration of universities and colleges.
Areas around the University of Nairobi, Kenyatta University, Usiu-Africa, Strathmore University, Daystar University, Riara University and other institutions have attracted student accommodation providers.
However, the opportunity is spreading beyond the capital. Kiambu County has become an important education corridor, with institutions like Jomo Kenyatta University of Agriculture Technology, Mt Kenya University and Zetech University.
Other university towns – including Eldoret, Nakuru, Kisumu, Mombasa, Kakamega, Meru, Bungoma, Embu and Machakos – also have sizeable student populations.
These markets can offer a different development equation. Land may be cheaper than in prime Nairobi locations, but rental rates can also be lower.
An investor, therefore, has to establish whether the student population can support the proposed rent and if there is sufficient demand.
Ndege says investors should examine the fundamentals of a location before committing money to student housing.
The number of students is only one consideration. An investor should also look at how many learners require private accommodation, the number of existing beds, planned competing developments, transport links and the ability of students or their parents to pay the proposed rent.
The risk of building too much
One of the risks is concentration. If several developers construct large numbers of similar beds around the same institution, supply could eventually outpace demand.
University policies can also influence the market. Changes in enrolment, campus expansion, accommodation policies or the way students attend classes can affect demand for private accommodation.
Financing costs present another risk. A development funded heavily through expensive debt can become difficult to sustain if interest costs rise before the project reaches stable occupancy.
Then there is the question of affordability. Students may want modern rooms, fast internet, security and recreational facilities, but their budgets remain constrained.
The challenge for developers is, therefore, to provide facilities that students value without pushing rent beyond what the target market can afford.
The growth of PBSA represents a broader change in Kenya’s property sector. Student housing was once largely viewed as a small-scale business where individual landlords converted houses into rooms and collected rent.
Institutional investors are now treating it as a specialised asset class requiring professional development, financing and management.
For students and parents, this could eventually mean greater choice and more consistent standards.
For developers, it opens a market supported by a large and continually replenished pool of potential tenants.
For investors, however, the fundamentals still matter. A building can have hundreds of beds, but its performance ultimately depends on where it is located, what students can afford, how effectively it is managed and whether demand continues to grow.
Kenya’s university student population of more than 631,000 provides a substantial potential market.
It should, however, be noted that the next phase of the student housing boom will not simply be about who can builds the most beds. It will be about who can provide the right accommodation, in the right location and at a price students and their parents can sustain.
That is likely to determine how Kenya’s emerging PBSA market develops from a collection of informal hostels into a mature institutional property sector.