In the heart of Kenya’s economic struggle, a silent and deeply personal crisis is taking root.
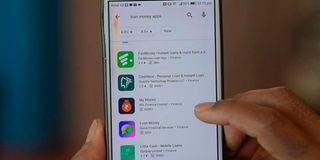
What started as a beacon of hope, quick loans at the tap of a screen, has turned into a labyrinth of financial despair. Kenya’s digital lending boom, once celebrated as a symbol of financial inclusion, has left behind a harrowing trail of human misery: shattered lives, relentless shame, and the suffocating fear of debt collectors.
For millions of Kenyans navigating stagnant incomes and the soaring cost of living, digital loans seemed like a lifeline. With just a few clicks, a desperate parent could pay school fees or cover an emergency hospital bill.
This easy access has fuelled a meteoric rise as over eight million Kenyans, roughly 16 percent of the population, turn to digital loans every month, collectively borrowing an eye- popping Sh15 billion monthly.
But beneath this promise of instant relief lies a web of predatory practices, unregulated fees, and relentless intimidation, trapping borrowers in cycles of debt that can feel impossible to escape.
Traditional bank loans in Kenya typically hover around 12 percent annually. Digital lenders, however, have been charging eye-watering rates: some demand up to 17 percent for 30 days, translating to annual rates of over 200 percent.
Hidden fees, daily penalties for late repayment, and convoluted terms make the true cost even worse. In many cases, borrowers “agree” to these conditions without understanding them, driven by desperation rather than informed choice.
This easy access has paradoxically fuelled a crisis of over-indebtedness. A 2017 FinAccess survey found that 14 percent of borrowers were juggling multiple digital loans.
Over 800,000 Kenyans caught in a dangerous cycle of borrowing from one app to pay off another. By November 2022, the Central Bank of Kenya (CBK) reported that 14 million accounts had been listed for defaulting on digital loans.
The consequences ripple far beyond household budgets. A 2019 study by FSD Kenya indicated that digital credit increased the probability of household debt distress by 22 percent and slashed household income by about 16 percent.
Many borrowers cut food budgets or sold personal belongings just to meet the impossible repayment demands.
Recognising the magnitude of the problem, the CBK took a decisive step in 2022. The Digital Credit Providers Regulations, gazetted in March of that year, finally placed digital lenders under regulatory oversight.
The Business Laws (Amendment) Act 2024, effective January 2024, further strengthened CBK’s authority to supervise the sector and enforce ethical practices.
The human toll is devastating. A taxi driver in Nairobi, borrowed money to pay a hospital bill. Barely two weeks later, he received a chilling text: “We will call your entire contact list if you don’t pay by 6pm.”
The threats came from more than 20 phone numbers in a single afternoon, pushing him into a state of panic.
A study by the Financial Sector Deepening (FSD) Kenya and CGAP found that some borrowers received more than 1,000 phone calls from over 60 different numbers, some in the dead of night, some at dawn.
Threats included exposing borrowers’ personal lives to family, friends, and employers, and unfairly blacklisting them with credit reference bureaus (CRBs).
To date, 85 Digital Credit Providers (DCPs) have been licensed out of more than 700 applications, signalling a determined effort to clean up the sector. CBK Governor Dr Kamau Thugge recently noted that consumer complaints have fallen significantly from around 4,000 cases monthly to just a handful.
However, the sheer volume of pending applications and the still-thriving unlicensed market reveal the long road ahead.
This crisis isn’t confined to the individual level. When families must devote large chunks of their income to service predatory loans, they cut spending elsewhere on education, health, and even basic nutrition.
These lost opportunities for growth stunt entire communities, eroding the very financial stability that digital lending once promised.
The psychological trauma and social shame of being hounded by lenders also breed anxiety and mistrust. Friends and family are co-opted as debt collectors, turning personal networks into battlegrounds of humiliation.
Worse still, easy credit has encouraged risky borrowing for non-productive uses like gambling, fuelling an economy of dependency rather than growth. The result: a society trapped between the promise of financial inclusion and the reality of financial enslavement.
The growing number of disputes surrounding digital lending in Kenya has increasingly found its way into courtrooms and police stations across the country.
According to data from the Kenyan Judiciary’s 2024 annual report, there were over 200 digital lending-related cases filed in the civil courts that year alone, mostly centred around data privacy breaches and defamation arising from aggressive debt collection practices.
In Nairobi, for instance, the Milimani Law Courts have become a focal point for these cases, handling lawsuits from borrowers who allege that lenders shared their personal contact lists and photographs without consent, leading to social stigma and, in some cases, job loss.
A landmark ruling in 2023 awarded a borrower Sh500,000 in damages against a digital lender for defamation after humiliating messages were sent to his employer and extended family.
Police stations, too, have become an unwilling arena in this escalating conflict. Between January and December 2024, the National Police Service received more than 1,000 complaints from borrowers who claimed to have been physically threatened or harassed by digital lenders’ debt collection agents.
In Kiambu County, for instance, a woman filed a police report in October 2024 alleging that she was ambushed at her home by three men posing as debt collectors for a popular lending app.
They threatened violence if she didn’t pay up immediately, an incident that highlighted the extreme measures used by some lenders and blurred the line between debt recovery and outright criminal extortion.
The Data Protection Act, 2019, which explicitly prohibits the misuse of personal data, has become a critical tool for borrowers seeking justice. Yet, enforcement remains patchy.
As of early 2025, the Office of the Data Protection Commissioner had received over 4,000 complaints of digital lenders misusing customer data, with only a fraction of those cases leading to formal investigations.
Experts warn that without robust enforcement of these laws, borrowers will remain vulnerable to predatory lenders who exploit gaps in regulation and oversight, highlighting the urgent need for comprehensive consumer protections in the digital lending space.
Experts agree that Kenya urgently needs stronger enforcement, not just regulation on paper. Caps on interest rates and clear, transparent loan terms are essential to protect borrowers from predatory fees.
The CBK must also crack down on the illegal practices of harassment and data misuse, treating them as human rights violations.
Also the prohibition of interest-based loans in Abrahamic religious teachings serves as a reminder that wealth should be earned through efforts, shared risks, and mutual benefits rather than through exploiting the financial vulnerabilities of others.
Lastly, financial literacy initiatives are equally critical. Borrowers must be empowered to understand loan terms and resist the seductive but dangerous lure of instant credit. Until then, the digital lending boom, once seen as a ticket to a better future, remains a noose for millions of
Kenyans, tightening with each unanswered call and unpaid debt. Kenya stands at a crossroads. In this digital age, technology can be either a tool for liberation or a weapon of exploitation. The choice is urgent and the consequences are deeply human.