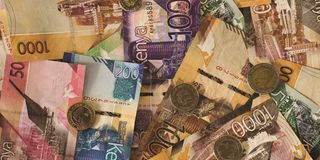
If you want to know how much money Kenya has, do not check the Central Bank. Check under our mattresses. Every Kenyan knows a mama mboga in Githurai who sleeps on a fortune of fifty shilling coins wrapped in a leso. She does not trust banks. Her neighbour, a boda rider, keeps his daily collection in his socks. In Kangema, my father kept money in a tin above the fireplace. We are a cash economy pretending to be modern.
It is time we made a radical decision: in five years, let Kenya cancel coins and notes and go fully digital. No more paper. No more metal. Only shillings in our phones and bank accounts.
Call it madness. But nations grow not by doing what is comfortable, but what is clever.
First, think of the money. Economists estimate Kenyans hold over Sh500 billion outside the banking system. That money does not build factories. It does not earn interest. It just sleeps. That Sh10,000 under the mama mboga’s mattress earns zero, but in a bank it would earn Sh800 a year and create a loan for another Kenyan. If that money were forced into banks through a phased digital switch, banks would be flooded with deposits. What do banks do with too much money? They lower interest rates. They beg you to take loans.
Today, a trader pays 20 per cent for a loan. In a cashless Kenya, she could pay 8 per cent. Cheap credit means more business, more expansion, more jobs for our sons who loiter in shopping centres.
Second, we would finally formalise Kenya. This is our greatest economic wound. We have about 4 million formal workers and over 18 million hustling in the informal sector. Yet KRA collects 90 per cent of income tax from the 4 million. The 18 million contribute 10 per cent. SHA tells the same sad story: out of 28 million registered, only 4 million formal employees and about 1 million informal pay consistently. The rest wait until cancer strikes; then we do harambees. Why? Because cash is invisible. A digital Kenya is visible.
When the carpenter in Kamukunji is paid via phone, his income is seen. The government does not need to add a single new tax. It just needs to see what is already there. As the Bible says, render to Caesar what belongs to Caesar; but how can Caesar collect if Caesar cannot see?
Third, credit will change from asset-based to cashflow-based. Today, a bank asks a young man in Murang’a, “What title deed do you have?” He has none, so he gets no loan. In a digital economy, the bank asks, “Let me see your cashflow.” His M-Pesa statement shows he sells 200 litres of milk daily at Sh50. That statement becomes his title deed. This is how China lifted millions. They did not ask for collateral; they read data. Our youth have data in plenty, but cash hides it.
Fourth, corruption will starve. Let us be honest. The traffic policeman on Kenol-Marua Road does not take bribes via PesaLink. He takes a crumpled Sh500 note. The chief who demands kitu kidogo for a bursary form wants cash. Once cash dies, a bribe must be sent via M-Pesa or bank. That leaves a permanent footprint. Even the most foolish bribe-taker knows EACC can follow a phone trail. We will not end corruption, but we will make it traceable, and what is traceable is feared.
Fifth, violent crime will lose its logic. Why rob a bank if there is no cash inside, only digits? Why pickpocket someone in Nairobi CBD if his pockets have no notes, only a phone with a PIN and biometrics?
Why break into a shop in Murang’a town at night? Thieves will be forced to become hackers. Hacking is bad, but it is white-collar and non-violent. I would rather lose money to a clever keyboard in Mulot village in Bomet than lose a son to a pistol in Kayole.
Sixth, monetary policy will finally work. Today, when CBK lowers rates to stimulate the economy, half the country does not feel it because half the money is outside banks. It is like pouring water into a jerrican with a hole.
A fully banked, digital money supply means CBK can steer the economy properly, control inflation and protect the shilling. What would this mean? IMF studies on digital economies show formalisation and cheaper credit can add 2 to 3 percentage points to GDP growth. For Kenya, that is an extra Sh300 to Sh400 billion per year. That is enough to employ a million youth, build 10,000 extra classrooms and ensure that when Githurai to town fare is Sh50, it can be paid without hunting for coins.
Of course, there are dangers. If we do it overnight, we will be India in 2016, where currency cancellation killed small traders. So we must phase it in five years.
In years one to four, we do mass education and infrastructure. We extend internet to every sub-location; we subsidise simple feature phones that transact offline via USSD for the cucu in Ndakaini who has never used a smartphone. We say to Safaricom, Airtel and banks: You will make billions from more deposits, so you must help us lay the rails.
Second danger is transaction cost. If you charge a mama mboga Sh10 to send Sh50 fare from Githurai to town, you have killed digital. So we zero-rate small transactions below, say, Sh500. Let telcos recover from float interest and high-value transfers, not from the hustle of the poor.
Third is lack of know-how. Our people learn fast. They learned M-Pesa faster than any European nation learned cards. Let chiefs, churches and schools teach digital literacy.
Fourth, the law. Our law says coins and notes are legal tender. In year four, Parliament must amend the Central Bank of Kenya Act and give one year of dual legality, where both cash and digital work, then cash ceases.
Fifth, anti-money laundering laws. If you suddenly ask a trader who has saved Sh2 million under his bed for 10 years to bank it, current AML rules will jail him. We must loosen them for five years to allow mopping up, then tighten again. There is an African saying: You do not shave a man in his absence. Let us carry everyone along.
Some will say the poor will suffer. The truth is, the poor already suffer because cash keeps them poor. The coin in her leso never grows. The note in his socks never gets a loan. Let us give that money wings, even if digital wings. Let us bury coins and notes, not to punish Kenyans, but to reveal them, to bank them, to fund them and to protect them.
Dr Irungu Kang’ata, PhD in Law, UoN, is the Governor of Murang’a County. Email: [email protected]