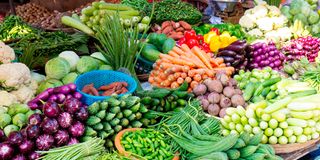
I am in my late 20s. I live with my parents in Eastlands, Nairobi. I have a college diploma, but I have been jobless since graduating from college. In January last year, I stopped looking for a job and started a small mama mboga business.
I sell veggies, fruits, and boiled eggs. Last month, I also started to sell githeri and chapos at lunch and in the evenings. I work from Monday to Saturday and make between Sh1,000 and Sh1,200 net profit per day. I have saved up Sh280,000 so far.
I would like to scale up, but I don’t know how to do it. I would also like to start investing. Currently, I save my money with a microfinance institution. I have not taken any loans yet, but I am considering taking a loan to grow my business and perhaps employ two girls to help with cooking duties.
If my business grows, I would like to pursue a degree. My main expenses are on personal care, my boyfriend, my little brother and tokens for my mum. Please advise me on how to start investing and how to grow my small business. – Florence
Your decision to start a business after unsuccessful job hunting has given you an income and a foundation for building wealth. Earning Sh1,000 to Sh1,200 daily and accumulating Sh280,000 is also really commendable. Your next step should be to strengthen the business, expand gradually and invest towards your education and financial security.
At six working days a week, your reported profit translates to approximately Sh26,000 to Sh31,200 monthly. Through proper bookkeeping, you should confirm that this is after all business expenses, including transport, fuel, and food wastage.
From your daily sales, start by setting aside money for stock replenishment and other business expenses. Then, set aside your daily savings allocation and transfer it to your savings account. Finally, allocate yourself a fixed amount for your expenses – household support, personal care, and supporting others as mentioned. Keeping this priority will help you control your spending, build your business and grow your investments consistently.
Next, review your microfinance account’s interest rate, charges and withdrawal terms. If your savings are earning you little or no interest, then inflation will gradually reduce your funds’ purchasing power. In this case, you can consider retaining about Sh50,000 or so in the microfinance account for working capital and modest business expansion while investing the remaining Sh230,000 in a safe investment account such as a Money Market Fund (MMF), Bond Fund or Treasury Bill. An MMF would be a practical starting point as it is straightforward to open and make regular contributions to.
If you transfer Sh230,000 to an MMF this month and add Sh1,000 per working day (assuming this is what you are already doing), your investment could grow to about Sh668,000 by the end of next year (December 2027) at an illustrative net return of 9 per cent per year. If you grow your business and increase your savings, this amount could become much higher. You can use the fund to cover emergencies, finance your degree studies and pursue other financial goals.
You may also want to evaluate your reasons for joining the microfinance institution you are banking with as opposed to the traditional bank or Sacco. This is especially given the terms of service, including on facilities, which are considered more expensive and less favourable amongst microfinance institutions when contrasted against conventional mainstream banks and/or Saccos.
For business growth, I would advise you to consider growing organically rather than undertaking a major expansion while the business is still within its teething years. Concentrate first on products with consistent demand and good profit margins. Since you introduced githeri and chapatis only last month, establish whether demand remains steady before committing to hiring the two employees. You could start with one assistant to help you increase production while learning how to supervise staff.
Evaluate this arrangement over two or three months. Additional sales should cover the assistant’s wages, ingredients, fuel and other expenses while leaving you with more profit than before. You can then increase production, add another assistant or introduce related products as demand justifies. Such a model will help you grow your business substantially in a more controlled way.
Another way to grow your client base is networking around the neighbourhood and tapping into construction sites where mama mboga food services come in handy.
As for loans, I would advise you to postpone borrowing. Your savings give you enough room at this stage to expand your business. You may consider debt later once you have identified and tested a clear opportunity with substantial growth potential, learnt to manage staff and developed a better understanding of the dynamics of your business environment.
Even as you do business bookkeeping, I would also urge you to check on your personal financial habits. This involves knowing exactly how much you spend on each of the expense items you have listed. For example, how much do you spend on your boyfriend? Is this a regular expense? Is he working and financially self-reliant?
By keeping your personal money in check, you will close personal loopholes that could leak money and undermine the hard work you are doing with your business.