A parliamentary committee wants the law changed to give the Controller of Budget (CoB) powers to report on and provide independent oversight of billions of shillings held in national and county government funds and levies.
The call by the National Assembly Committee on Constitutional Implementation Oversight, contained in a report to the House, comes amid concerns that a majority of the 75 funds and levies at the national level, as well as many others in the counties, are blind spots and potential cash cows.
There is also the Affordable Housing Levy, which has collected about Sh65 billion deducted from Kenyans’ earnings for the construction of low-cost housing units, but whose use remains outside oversight.
The report on the status of implementation of the Constitution quotes Dr Nyakang’o as saying the loophole in the law “prevents any independent oversight” of billions held in funds and levies, “severely undermining” her supervisory role over public finances.
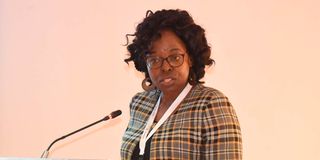
Controller of Budget Margaret Nyakango,
Photo credit: File | Nation Media Group
“The Controller of Budget clarified that all funds and levies fall outside her oversight mandate due to their classification as funds and levies rather than budgeted funds,” the report states.
The MPs also want the Controller of Budget Act amended to include enforcement powers so that recommendations are implemented, restrictions on economic reporting are removed, and sanctions for violations are provided.
Dr Nyakang’o recently admitted that her office — one of the two constitutional independent offices alongside that of the Auditor-General — lacks visibility over standalone government funds and levies.
She said that because these statutory and special funds operate outside the Consolidated Fund, her office lacks the statutory mechanisms to directly oversee or track how the billions of shillings are spent.
“Anything called a fund or a levy, we will not see it. They are not part of the Consolidated Fund,” Dr Nyakang’o said. “My oversight powers are directly tied to withdrawals from the Consolidated Fund.”
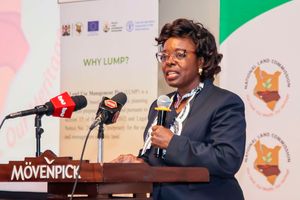
Auditor-General Nancy Gathungu, during the launch of guidelines for land use and management plans for land held by public agencies at the Mövenpick Hotel in Nairobi on July 1, 2026.
Photo credit: Wilfred Nyangaresi | Nation Media Group
This comes as Auditor-General Nancy Gathungu, in a document before Parliament, raised concerns that more than Sh30 billion held in county public funds may have been misappropriated because the funds operate outside the Integrated Financial Management Information System (IFMIS) and, therefore, lack adequate oversight.
The PFM Act provides for the establishment of county public funds with the approval of the County Executive Committee and the County Assembly. However, Ms Gathungu warns that operating county funds outside IFMIS — which has been instrumental in promoting prudent and transparent use of public resources by increasing the visibility of government financial transactions — potentially increases the risk of fraud and corruption.
“County funds operate outside IFMIS and, therefore, payments made by these funds may not be properly recorded as the management information system used to record business transactions is mainly manual,” Ms Gathungu warns.
Dr Nyakang’o identified the Social Health Insurance Fund (SHIF), Affordable Housing Levy Fund, Hustler Fund, National Infrastructure Fund (NIF) and Sovereign Wealth Fund, among others, as blind spots — pools of money her office cannot trace once collected.
She said key constitutional safeguards had been bypassed and questioned why multi-billion-shilling funds and levies were allowed to operate without strict, real-time reporting mechanisms to scrutinise expenditure before it occurs.
She cited the Primary Healthcare Fund, where cash is approved and released as lump-sum transfers. Once it leaves the Central Bank of Kenya, it sits in individual county or departmental accounts in commercial banks, leaving her unable to track its use or verify whether the money is available for national projects.
Ms Gathungu’s document shows that the 47 counties have 267 funds, with 209 belonging to county executives and 58 owned by county assemblies.
The most common funds include the county education fund, bursary fund, county car loan and mortgage scheme fund, county enterprise fund and social protection fund.
Others include the county emergency fund, county asset leasing fund, county cooperative development revolving fund, county business stimulus fund, county persons with disability fund and county youth and women enterprise development fund.
Ms Gathungu revealed that in the three financial years ending June 30, 2024, the 209 county executive-owned funds received Sh29.3 billion, while the 58 county assembly funds received Sh1.23 billion.
CIOC, in its report to the House, highlighted the potential for abuse arising from the OCoB’s inability to oversee the billions held in these funds.
To ensure effective oversight of public funds, the committee says amendments to the PFM Act are critical to bring all special funds and levies under the OCoB’s oversight.
“The CoB's oversight mandate is severely undermined by legislative limitations and lack of enforcement mechanisms,” the CIOC report says, adding that “the funds and levies exclusion from oversight creates significant accountability gaps.”
CIOC also wants the National Treasury to implement the OCoB-Central Bank of Kenya (CBK) integrated payment system to track funds from approval to expenditure and ensure accountability.
Early this year, Housing and Urban Development Principal Secretary Charles Hinga told the National Assembly Housing, Urban Planning and Public Works Committee that between Sh5 billion and Sh6 billion is collected every month through housing levy deductions from Kenyans.
According to the PS, the government is investing the money, which is meant to finance the construction of affordable houses, in Treasury bills and bonds, despite the OCoB’s revelations that the delivery of housing units remains behind schedule.
President William Ruto, through his affordable housing programme, undertook to construct at least 200,000 housing units annually to address the housing deficit and create jobs for low- and middle-income earners.
To finance the affordable housing programme, Parliament enacted the Affordable Housing Act, which came into force on March 19, 2024.
The Act establishes a mandatory levy to fund affordable housing projects as part of President Ruto’s Bottom-Up Economic Transformation Agenda (BETA).
The levy is charged at a rate of 1.5 per cent of an employee’s gross monthly income, with a matching contribution from the employer.
In her submission to CIOC, Dr Nyakang’o identified legislative and operational constraints as “critical limitations” in the Controller of Budget Act that frustrate her work.
For instance, the law bars her office from reporting on economic developments and fiscal forecasts, while it also lacks enforcement powers to ensure implementation of its recommendations.
“For the avoidance of doubt, the reports submitted to Parliament shall not include reports on recent economic developments and outlook, including revenue, grants and loans forecasts and receipts,” Section 9(4) of the Controller of Budget Act states.
The CoB also identified inadequate sanctions for violations of public finance management laws and restricted access to critical financial information from some national government entities as other hindrances to her work.
Circumvent financial controls
The committee also revealed that wasteful expenditure of public funds continues despite the existence of oversight institutions, noting that multiple unauthorised accounts indicate deliberate attempts to circumvent financial controls.
Besides operating outside IFMIS, Ms Gathungu decried the unregulated creation of funds by counties, saying this creates challenges for oversight because the Auditor-General “may not be aware when new funds are created.”
There is also a lack of documented budgeting processes for the funds, reduced oversight and accountability, and inefficiencies in their financial operations.
“Counties are not limited in the number of funds they can set up. They can set up and wind up funds without any limitation in numbers,” Ms Gathungu says, adding: “This may not only create duplication of departmental roles but may also increase administration costs without commensurate benefits.”
The document notes that budgets for the funds are “seldom” presented to county assemblies or independent governance structures for approval as required by the PFM Act.
It also reveals that expenditure incurred by the funds is not captured in quarterly reports to the Controller of Budget because it is “treated as part of expenditure for the executive or county assembly.”
Ms Gathungu says the expenditure is reported in gross as transfers to other government entities, reducing the level of oversight and accountability provided for under the PFM Act.
The Constitution, the PFM Act and its regulations require any amount not spent by a public entity at the end of a financial year to be repaid to the County Revenue Fund (CRF).
However, the Auditor-General notes that county executives have been using county funds to sidestep “this requirement”, as cash not spent in a financial year by the county funds is not repaid to the CRF for re-approval by county assemblies and expenditure approval by the Controller of Budget.